

What Happens When Insurance Totals Your Car?

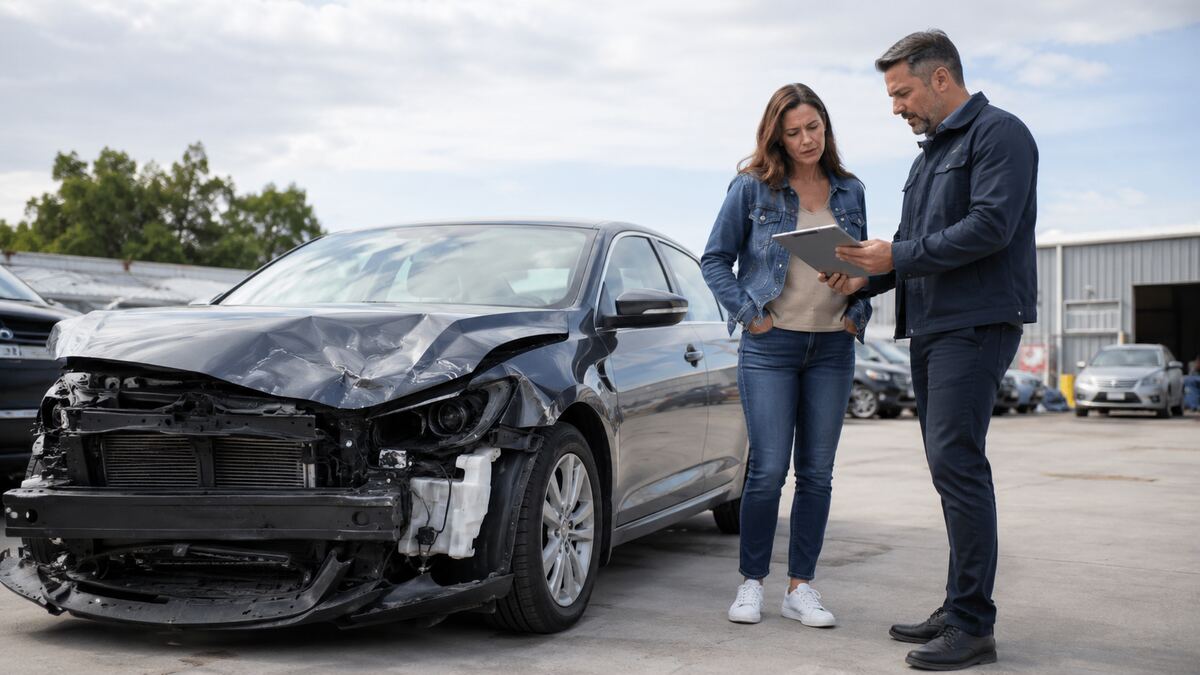
When an insurance company totals your car, it has determined that repairing the vehicle is not economically practical under the policy and applicable state rules. The insurer will value the car immediately before the crash, subtract any applicable deductible or owner-retained salvage amount, address the lender’s interest if the car is financed, and issue a total-loss settlement. You do not have to accept an inaccurate valuation without asking questions or supplying better evidence. Just as important, resolving the vehicle-damage claim does not necessarily resolve a separate injury claim—but you should read every release carefully before signing it.
If another driver caused the collision and you were hurt, a car accident lawyer can protect the injury claim while the property-damage process moves forward. Strong Law also handles broader disputes through its personal injury practice.
Video summary: Attorney Jed Strong explains why drivers should begin looking for replacement transportation promptly after a total-loss decision: payment and the end of rental-car benefits can follow quickly. Those timeframes are not identical in every claim. The cutoff can depend on the policy, applicable state law, which insurer is paying, and when a reasonable total-loss offer is made. Ask the adjuster to confirm the final covered rental date in writing rather than relying on a general rule.
What Does It Mean When Insurance Totals Your Car?
A “total loss” is an insurance classification. It does not always mean the vehicle is crushed beyond recognition. A car may look repairable but still be totaled when the expected repair expense, hidden-damage risk, and salvage value make repair impractical compared with the car’s pre-crash value. State rules and policy language affect the calculation, so insurers do not use one nationwide percentage in every claim.
The insurer normally inspects the vehicle, reviews a repair estimate, and determines its actual cash value. The Idaho Department of Insurance’s auto-claims guidance, for example, explains that a vehicle need not be demolished to qualify as a total loss and that the insurer ultimately determines whether repair is practical. That is a useful general illustration, but your own state’s rules and your policy control your claim.
How Does an Insurer Decide a Car Is a Total Loss?
The adjuster starts with the visible damage and a repair estimate. Modern vehicles have expensive sensors, airbags, cameras, structural components, and calibration requirements. Damage found during a teardown can push an apparently repairable car across the total-loss threshold.
Depending on the state and policy, the decision may use a percentage of actual cash value or a formula comparing repair cost plus salvage value with the vehicle’s value. Because the standards vary, ask for the figures used:
- The vehicle’s proposed pre-loss actual cash value
- The current repair estimate and expected supplements
- The salvage value
- The state rule or policy provision applied
- A copy of the complete valuation report
What Happens After the Total-Loss Decision?
Once the insurer declares a total loss, the property-damage claim generally shifts from repair to valuation and transfer. The exact order differs, but the process commonly looks like this:
| Claim step | What usually happens | What you should verify |
|---|---|---|
| Valuation | The insurer calculates the car’s pre-crash actual cash value. | VIN, trim, options, mileage, condition, and comparable vehicles |
| Settlement calculation | Applicable taxes or fees may be added, and a deductible or salvage value may be subtracted. | Every addition and deduction and the rule supporting it |
| Loan or lease review | The insurer confirms the lienholder and payoff information. | The current payoff amount and whether GAP coverage exists |
| Vehicle transfer | You may sign title documents and release the vehicle, or elect to retain it if allowed. | Personal items, plates, title requirements, and salvage deduction |
| Payment | The check may include the owner and lienholder or go to the lender first. | Payees, amount, mailing or electronic-payment details, and any release language |
Before the vehicle leaves your control, remove personal property, photograph it, save dash-camera footage, and ask what happens to the plates. Keep the title documents, settlement calculation, and communications. For the earlier stages, read our guide to the auto accident claim process.
How Is the Total-Loss Settlement Calculated?
Most ordinary auto policies pay actual cash value rather than the price of a brand-new replacement vehicle. A simplified first-party calculation often begins with the accepted actual cash value, adds any amounts required by state law, and subtracts the collision deductible. If you keep the vehicle, the insurer will generally also subtract its salvage value. A third-party claim against an at-fault driver’s insurer usually does not apply your own collision deductible, although liability and available coverage can create other complications. Coverage can also become more complicated when the damaged vehicle belongs to someone else; our guide explains who pays after a crash in a friend’s car.
Taxes, title charges, registration fees, and related expenses receive different treatment across states. Illinois regulations, for example, allow an insurer to pay certain sales taxes and transfer or title fees at settlement or reimburse them after a replacement purchase under state-specific deadlines. Do not assume that Illinois process applies elsewhere; ask the adjuster to itemize what is included under the law governing your claim.
What Is Actual Cash Value?
Actual cash value, often called ACV, is generally the vehicle’s value immediately before the covered loss—not what you originally paid, what you still owe, or the price of the newest version of the same model. Insurers commonly rely on recent comparable vehicles and adjust for differences in year, trim, mileage, equipment, condition, and local market.
Valuation reports can contain costly mistakes. The wrong trim, missing option package, incorrect mileage, or unjustified condition deduction can reduce the offer. Compare the report with the VIN, window sticker, records, photographs, and actual features. Well-matched local listings can help expose unrealistic comparables, even though asking prices are not final sales prices.
Can You Negotiate the Insurer’s Valuation?
Yes. The total-loss label may be final, but the proposed value can still be challenged with evidence. Begin by requesting the full valuation report and asking the adjuster to explain each comparable vehicle and adjustment. Then check:
- Whether the report lists the correct make, model, year, trim, drivetrain, and options
- Whether mileage and pre-crash condition are accurate
- Whether comparable vehicles are truly similar and available in a reasonable local market
- Whether unsupported “condition,” “dealer,” or “projected sold” adjustments were applied
- Whether recent major maintenance or new tires are documented
- Whether required taxes and transfer fees were included
Send a written counter with corrected facts, photographs, service receipts, and strong local comparables. If it is a claim under your policy, read the appraisal clause; it may provide a dispute process. The Oregon Division of Financial Regulation’s auto-insurance FAQs also explains that a total-loss payment is based on ACV rather than the loan balance.
What Happens If You Still Owe Money on the Car?
A loan does not increase the car’s insurance value. Because a lienholder has a financial interest, the insurer may pay the lender directly, name the owner and lender on one check, or pay the lender first and send any remaining equity to the owner.
If the settlement exceeds the payoff, the excess generally goes to the owner after the lien is satisfied. If the payoff exceeds the settlement, the borrower normally remains responsible for the shortage. Continue making required payments until the lender confirms the loan is paid and closed; a pending insurance claim does not automatically pause the contract.
How Can GAP Coverage Help?
Guaranteed Asset Protection may cover some or all of the difference between the insurer’s vehicle payment and the remaining loan or lease balance. The Consumer Financial Protection Bureau describes GAP as an optional product intended for that difference when a financed vehicle is stolen or totaled.
GAP is not a substitute for a fair valuation, and the contract may exclude the deductible, missed payments, late fees, warranties, or rolled-in negative equity. Notify the provider promptly and keep its checklist, the insurer’s valuation and settlement, the payoff letter, finance agreement, and payment history.
Can You Keep the Totaled Car?
Sometimes, but owner retention has consequences. The insurer usually reduces the settlement by the vehicle’s salvage value. State title, inspection, registration, and insurance requirements may then limit whether and how the vehicle can return to the road. A lender may also object because its collateral has been declared a total loss.
Before choosing owner-retained salvage, obtain the deduction in writing and investigate your state’s title rules, repair cost, parts availability, inspection process, future insurability, and resale value. The decision may make sense for a specialty vehicle or a car used only for parts, but a smaller check is only one part of the cost.
What Happens to Your Rental Car?
Rental benefits often end shortly after the total-loss valuation or settlement offer, but there is no single nationwide deadline. First-party rental reimbursement is controlled largely by the policy. A third-party insurer’s obligation depends on liability, reasonableness, and applicable law. The adjuster may give you little time to find a replacement vehicle.
Ask three questions immediately: What exact date and time does coverage end? Which charges remain covered? Where must the rental be returned? Get the answers in writing. A valuation dispute may not extend rental coverage, so plan transportation while preserving your objection.
Does the Total-Loss Payment Affect Your Injury Claim?
Vehicle damage and bodily injury are usually evaluated as different parts of a claim. Accepting payment for the totaled vehicle therefore does not automatically mean you have settled medical expenses, lost income, pain, disability, or other injury damages. The wording of the document you sign matters, however. A property-only release should be limited to property damage; a broad release may attempt to resolve every claim arising from the collision.
Do not sign a release you do not understand. If you are still treating, your diagnosis is uncertain, or an adjuster is pressing for a complete settlement, get legal advice first. Also be careful with recorded statements and questions that mix vehicle facts with your physical condition. Our guide to questions insurance adjusters may ask explains why precise, truthful answers are important.
What Documents Should You Gather?
A well-organized file makes it easier to identify a valuation error and keep the property and injury claims separate. Save:
- The declarations page and complete applicable policy
- The repair estimate, supplements, photographs, and total-loss notice
- The complete valuation report and comparable-vehicle data
- The title, registration, purchase documents, window sticker, and option list
- Service records, tire receipts, and pre-crash photos showing condition
- The lender’s current payoff letter and any GAP contract
- Rental agreement, towing and storage records, and related receipts
- Every settlement offer, release, email, text, and adjuster note
Keep separate records for medical care, work loss, and other injury damages. A police report can also help establish crash facts even though it does not set the vehicle’s market value; see how to obtain a car accident police report.
What Can You Do If the Insurer Will Not Correct the Offer?
Escalate the dispute in writing. Identify the exact error, attach the evidence, state the value you believe the evidence supports, and ask for a written response. For a first-party claim, review the appraisal provision and all deadlines. For a third-party claim, consider whether using your own collision coverage is practical; your insurer may later pursue the at-fault party, subject to the policy and state law.
You may also contact the regulator in your state. The NAIC’s state insurance department directory provides regulator contact information and complaint links. A regulator can review compliance and claim-handling issues, but it may not decide every factual dispute over price. Preserve contractual and legal deadlines while a complaint is pending.
When Should You Talk to a Car Accident Lawyer?
A lawyer is not necessary for every straightforward property-damage claim. Legal advice becomes more important when the crash caused injuries, fault is disputed, the available insurance may be inadequate, the adjuster requests a broad release, or the insurer is using the property settlement to pressure the entire claim. Serious injuries can take time to diagnose and value, while legal filing deadlines continue to run.
Strong Law can review the collision, insurance coverage, communications, and proposed releases and explain which parts of the claim may require immediate action. The goal is not to turn a simple valuation question into unnecessary litigation. It is to prevent the quick resolution of a car payment from cutting off a much larger injury claim.
Frequently Asked Questions About Totaled Cars
How does an insurance company decide that a car is totaled?
The insurer compares the vehicle’s pre-crash value with the expected repair expense, salvage value, and other claim costs under the policy and applicable state rules. A vehicle can be totaled even when it is technically repairable. Ask for the repair estimate, valuation report, salvage figure, and rule used.
Can I negotiate the value of a totaled car?
Yes. Review the valuation report for errors in the VIN, trim, options, mileage, condition, and comparable vehicles. Submit corrections, local comparable listings, photographs, and maintenance records in writing. If the claim is under your policy, check whether an appraisal clause applies.
What happens if I owe more than the totaled car is worth?
The insurance payment is generally based on the vehicle’s value, not the loan balance. The settlement usually goes to the lender first, and you remain responsible for any shortage unless GAP coverage or another agreement applies. Keep making required payments until the lender confirms otherwise.
Can I keep my car after it is declared a total loss?
You may be able to keep it, but the insurer generally subtracts salvage value from the settlement. State salvage-title, inspection, registration, and insurance rules may apply. Confirm the financial and legal consequences before choosing owner retention.
How long will insurance pay for a rental after a total loss?
There is no universal deadline. The answer depends on the policy, applicable state law, which insurer is handling the claim, and the timing of the total-loss offer. Ask the adjuster to provide the exact covered-through date and return instructions in writing.
Does accepting a total-loss check settle my injury claim?
Not necessarily. Property damage and bodily injury are usually separate, but the language of any release controls what you give up. Confirm that a property settlement is limited to property damage and obtain legal advice before signing a broad release.
Get Clear Answers Before You Sign
A total-loss claim can move quickly while the effects of a crash are still unfolding. Verify the valuation, loan payoff, GAP terms, rental deadline, title consequences, and scope of every release before you agree. If you were injured or the insurer is trying to resolve more than the vehicle claim, request a free case review from Strong Law. There is no obligation to hire the firm after the consultation.
This article provides general information, not legal advice. Insurance policies and state laws differ, and the best response depends on the facts of the claim.
See If Your Injury Claim May Qualify
Answer a few quick questions to help Strong Law understand what happened and whether your claim may qualify for a free review.
