

Motorcycle Accident Claim Process: 7 Steps Explained

Video overview: Jed Strong explains two issues that make motorcycle claims different from ordinary auto claims: documenting damage to the helmet, riding gear, and other personal property, and carefully reviewing motorcycle-specific PIP, medical-payments, and uninsured/underinsured-motorist coverage.
A motorcycle accident claim usually moves through seven stages, from protecting your health and preserving evidence to reviewing insurance coverage and negotiating a resolution. The basic framework resembles an auto claim, but motorcycles create additional issues involving rider visibility, severe injuries, damaged safety gear, bike inspections, and separate motorcycle policies. This guide explains the process without replacing advice about the law in your state.
How Does the Motorcycle Accident Claim Process Work?
A motorcycle accident claim generally involves seven overlapping steps: report the crash, seek medical care, notify the insurers, preserve evidence, document motorcycle and gear damage, identify every available coverage, and present a supported demand. If the insurer will not offer a fair resolution, the final stage may include mediation, arbitration, or a lawsuit.
- Protect your safety and report the crash.
- Get medical care and follow the treatment plan.
- Open the appropriate insurance claims.
- Preserve evidence and investigate responsibility.
- Document the motorcycle, helmet, gear, and personal-property damage.
- Review every potentially available insurance policy.
- Calculate the losses and negotiate or litigate the claim.
Several of these steps happen at the same time. For example, medical treatment may continue while the parties investigate fault and the insurers inspect the motorcycle. For a broader explanation that applies to passenger vehicles as well, see our guide to the basic auto accident claim process.
Step 1: What Should You Do Immediately After a Motorcycle Crash?
Move to a safe place if you can do so without increasing the risk of injury, call 911 when anyone may be hurt, and request a police response. Exchange contact and insurance information, but avoid guessing about what happened or accepting blame at the scene.
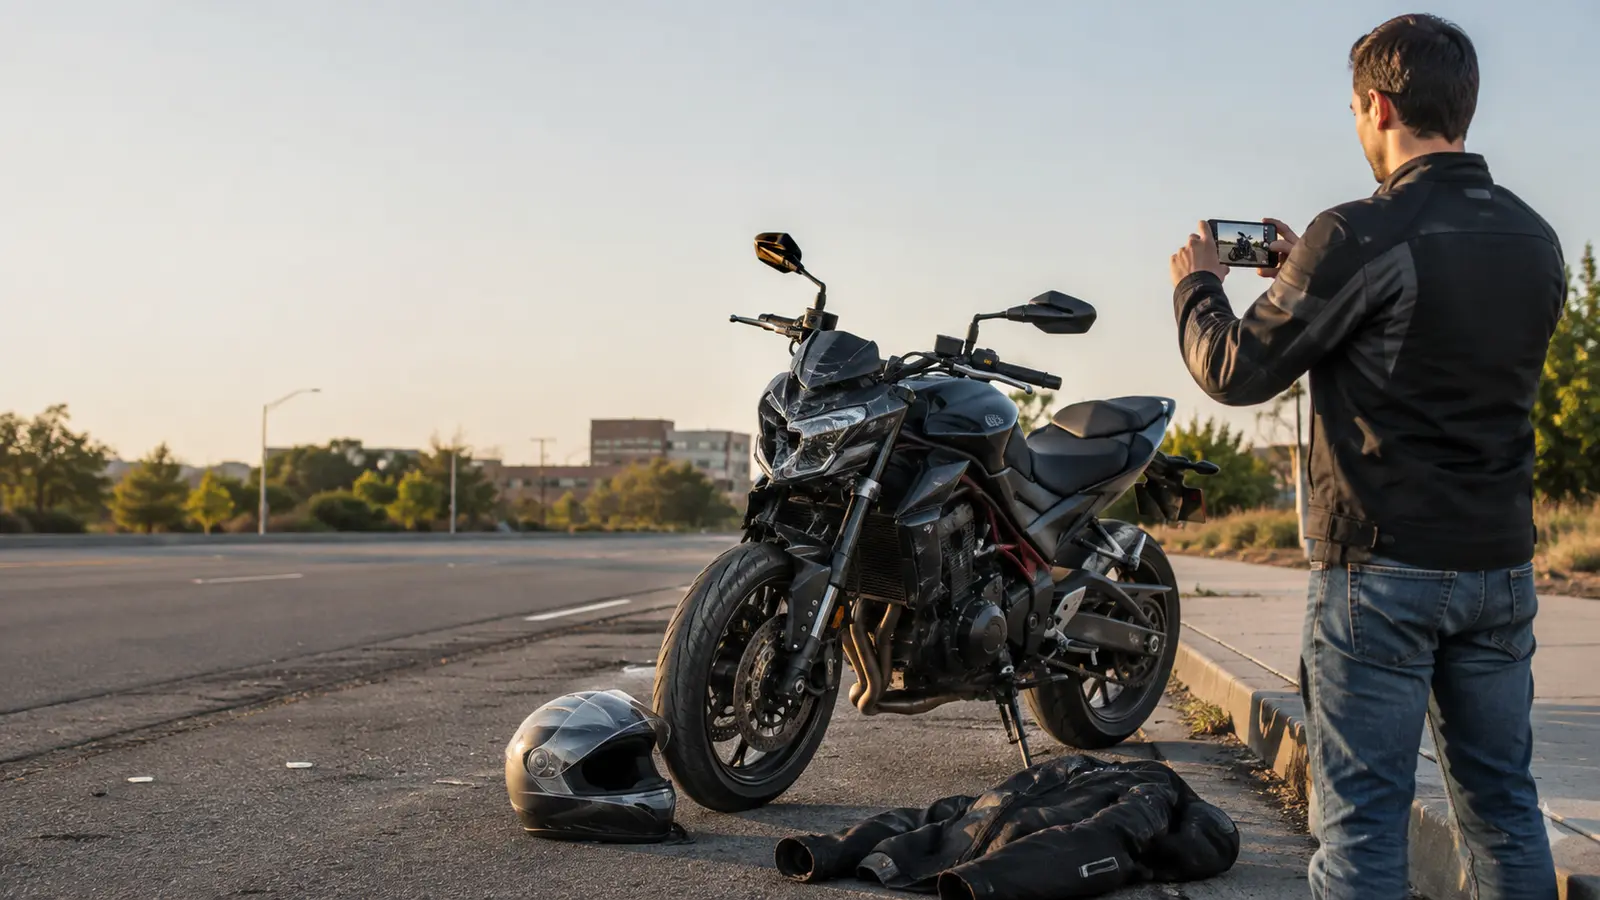
If conditions allow, photograph the motorcycle, every involved vehicle, debris, skid marks, traffic controls, weather, road defects, and the wider intersection or roadway. Get witness names and contact information. Write down the responding agency, report number, tow company, and the location where the motorcycle will be stored.
The National Association of Insurance Commissioners also recommends collecting vehicle, witness, officer, location, weather, and road-condition information after a collision.
Step 2: Why Does Early Medical Care Matter?
Motorcycle crashes can cause injuries that are not immediately obvious. Adrenaline may temporarily mask pain, and symptoms involving the head, neck, spine, joints, or internal organs can change after the scene. Seek appropriate medical attention and clearly explain every symptom and how the crash occurred.
Follow the treatment plan, attend appointments, and tell the provider when symptoms improve, worsen, or limit daily activities. Keep copies of bills, discharge instructions, referrals, work restrictions, and receipts for necessary out-of-pocket expenses. Accurate medical records help providers treat the injury and help connect the resulting losses to the crash.
Step 3: How Do You Open the Insurance Claims?
Most policies require prompt notice, so report the crash to your motorcycle insurer as soon as reasonably possible. A claim may also be opened with the at-fault driver’s liability insurer. Depending on the facts and the policy, separate claims may address injuries, motorcycle repairs or total loss, towing and storage, damaged gear, and uninsured or underinsured-motorist benefits.
Keep a claim log with the insurer’s name, claim number, adjuster, telephone number, email address, and the date and substance of each conversation. Provide accurate information, but do not speculate about your injuries, speed, visibility, or fault. Before giving a recorded statement to another party’s insurer, make sure you understand who is requesting it, whether your policy requires it, and how the statement may be used.
Step 4: What Evidence Makes a Motorcycle Claim Stronger?
Motorcycle cases often involve disputes about whether the driver saw the rider, who had the right of way, whether the rider was positioned safely, and how the impact occurred. Useful evidence may include:
- Crash-scene photographs, videos, and measurements.
- Traffic-camera, business-security, doorbell, or dash-camera footage.
- Witness statements and the police crash report.
- Damage patterns on the motorcycle and other vehicles.
- Electronic information from vehicles, phones, or navigation devices when legally obtainable.
- Road-design, construction, lighting, weather, or maintenance records.
- Medical records documenting injuries and physical limitations.
Some evidence can disappear quickly. Video may be overwritten, vehicles may be repaired, and road conditions may change. Preserve what you control and send appropriate preservation requests when another person, business, or government agency controls important evidence.
Step 5: Why Should You Document the Motorcycle, Helmet, and Riding Gear?
The property claim is broader than the motorcycle alone. Photograph every side of the bike before repairs or disposal, and preserve repair estimates, towing bills, storage charges, accessory receipts, maintenance records, and evidence of the motorcycle’s pre-crash condition and value.
Also inspect and photograph the helmet, jacket, pants, gloves, boots, phone, watch, luggage, communication equipment, and other damaged personal property. Record the manufacturer, model, age, purchase price, and current replacement cost when available. Keep the items until the insurer has had a reasonable opportunity to inspect them, and follow the helmet manufacturer’s safety guidance after an impact.
The National Highway Traffic Safety Administration explains the importance of DOT-compliant helmets and protective riding gear. Damage to safety equipment should be treated as a real loss, not an afterthought.
Step 6: Which Insurance Coverages May Apply?
A motorcycle usually has its own policy, and its terms may differ from an automobile policy. Do not assume that coverage available on a car automatically applies to the motorcycle. Review the declarations page, policy, and endorsements for:
- Bodily-injury liability: Coverage under the responsible party’s policy for injuries caused by that insured.
- Property-damage liability: Coverage that may pay for the motorcycle and other damaged property.
- Collision and comprehensive: First-party coverage that may apply to damage to the motorcycle, subject to the policy and deductible.
- Medical payments or PIP: Coverage for certain medical expenses or related losses when included and applicable.
- Uninsured/underinsured motorist coverage: Protection that may apply when the responsible driver has no insurance or insufficient limits.
- Accessory or custom-equipment coverage: Additional protection that may be needed for aftermarket parts and upgrades.
Coverage names, requirements, exclusions, limits, offsets, and claim procedures vary by state and policy. The NAIC recommends reviewing uninsured and underinsured motorist protection and understanding the policy before a crash. Ask the insurer for a complete policy if you only have the declarations page.
Step 7: How Are Motorcycle Accident Claims Resolved?
Once the injuries, responsibility, coverage, and losses are sufficiently documented, the claimant or attorney may submit a demand package. It can include the crash evidence, medical records and bills, wage-loss proof, property documentation, photographs, expert opinions when necessary, and an explanation of how the injuries affected the person’s life.
The insurer may accept the demand, deny responsibility, dispute part of the claim, or make a counteroffer. Negotiations may continue while additional records are collected. If the parties cannot reach a fair agreement, the available next steps can include mediation, arbitration when required or agreed upon, or litigation.
Do not sign a release until you understand which claims and parties it covers. A final release usually ends the listed claims, even if additional symptoms, expenses, or insurance issues appear later.
How Long Does a Motorcycle Accident Claim Take?
There is no single timeline. A straightforward property claim may resolve relatively quickly, while an injury claim can take months or longer. The timing depends on medical recovery, disputed fault, available coverage, the number of responsible parties, evidence collection, insurer cooperation, and whether a lawsuit becomes necessary.
Deadlines also vary by state, defendant, policy, and claim type. Claims involving a government vehicle, unsafe public roadway, minor, death, or uninsured-motorist dispute may involve special notice rules or shorter deadlines. Waiting for the insurer to respond does not necessarily extend a legal deadline.
What Makes Motorcycle Claims Different From Car Claims?
- Riders have less physical protection, so injuries may be more severe.
- Drivers may claim they did not see the motorcycle, creating visibility and rider-bias disputes.
- The motorcycle, helmet, protective gear, electronics, and accessories may create several property losses.
- Motorcycle policies may provide different medical, PIP, UM/UIM, accessory, and collision coverage than auto policies.
- Repair, valuation, salvage, storage, and safe-equipment-replacement issues may require specialized documentation.
These differences are why a claim should be built around motorcycle-specific evidence rather than treated as a smaller version of a car claim. Strong Law’s motorcycle accident attorneys can review how the process and available coverage apply to a particular crash.
What Mistakes Can Weaken a Motorcycle Accident Claim?
- Discarding the helmet, riding gear, damaged parts, or receipts before they are documented.
- Allowing the motorcycle to be repaired, sold, or destroyed before a needed inspection.
- Posting crash details, photographs, physical activities, or settlement discussions publicly.
- Missing treatment without explaining legitimate scheduling, transportation, or medical reasons.
- Assuming the at-fault driver’s policy is the only available coverage.
- Accepting a final settlement before the injuries and all covered losses are understood.
Frequently Asked Questions
Who pays for a damaged motorcycle helmet and riding gear?
The responsible driver’s property-damage coverage may pay for damaged gear, while coverage under the rider’s motorcycle policy may also apply. Payment depends on responsibility, policy language, state law, proof of ownership, and documentation of the damage and replacement value.
What if the driver says they did not see the motorcycle?
Failing to see a motorcycle does not by itself decide responsibility. The investigation should examine right of way, turning movements, lane position, speed, lighting, sight lines, traffic controls, witness accounts, video, and physical damage.
Can a rider make a claim if they were not wearing a helmet?
Possibly. Helmet laws and the effect of helmet use on compensation vary by state and by the injuries being claimed. Not wearing a helmet does not automatically establish who caused the collision, but it can create a separate dispute that requires state-specific analysis.
Will a motorcycle policy pay medical bills?
It depends on the policy. Some motorcycle policies include medical-payments coverage, PIP, or uninsured/underinsured-motorist benefits, while others do not. Health insurance or another policy may also be involved. Review the complete policy rather than assuming automobile coverage applies.
Do you have to accept the insurance company’s first offer?
No. An offer can be evaluated against the evidence, policy limits, medical information, lost income, property losses, and applicable law. However, every offer should be reviewed carefully because rejecting it can affect the time and risk required to resolve the claim.
How long do you have to file a motorcycle accident claim?
The deadline depends on the state, defendant, policy, and type of claim. Government claims and insurance-policy notices may have different requirements from the deadline for filing a lawsuit. Obtain state-specific guidance early instead of relying on a general internet deadline.
Because laws and insurance rules vary by location, riders can also review guidance from our Tacoma motorcycle accident lawyers, Salt Lake City motorcycle accident lawyers, and Albuquerque motorcycle accident lawyers.
Talk With Strong Law About a Motorcycle Accident Claim
If you were injured in a motorcycle crash, Strong Law can review the evidence, insurance policies, property losses, and deadlines that may apply. Contact Strong Law to request a free consultation.
This page provides general information and is not legal advice. Laws, deadlines, and insurance coverage vary by state and by the facts of each claim.
See If Your Injury Claim May Qualify
Answer a few quick questions to help Strong Law understand what happened and whether your claim may qualify for a free review.
